Choosing a business structure may seem simple when you first start. But as revenue grows, risk increases, and tax planning becomes more important.
Your structure affects how you pay tax, how much personal liability you carry, how profits can be distributed, and how easily the business can grow.
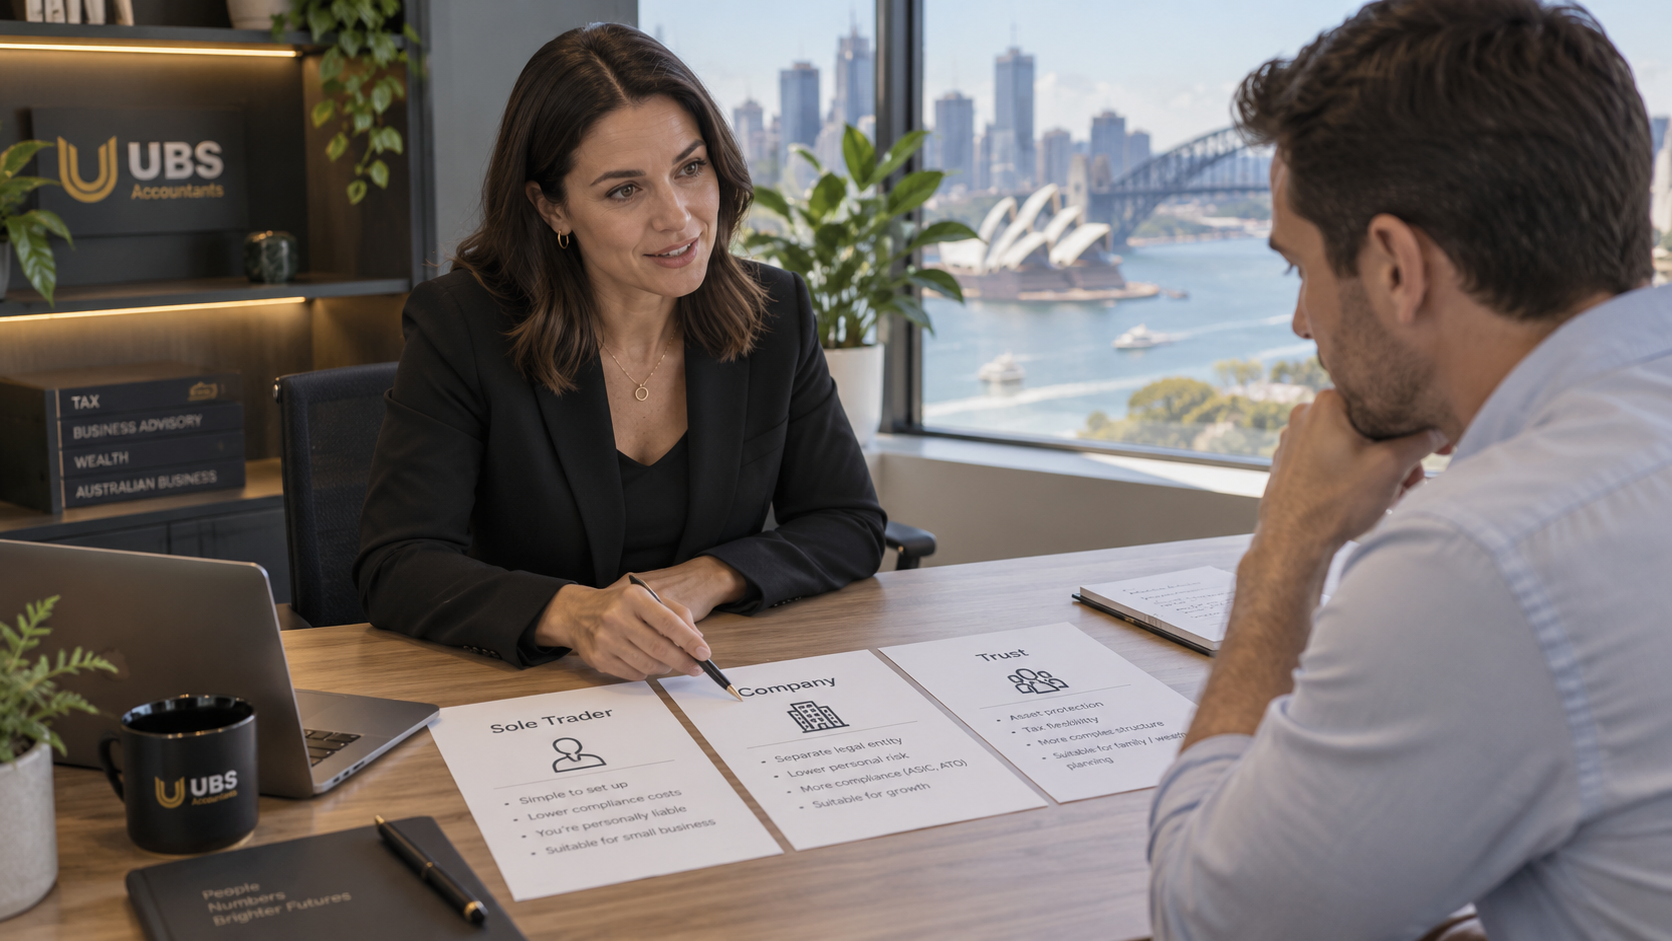
For many Sydney business owners, the choice comes down to three options: sole trader, Pty Ltd company, or a Discretionary Family Trust. The right structure depends on your profit, risk, ownership plans, and long-term goals.
Sole Trader: Simple, but You Carry the Risk
A sole trader is usually the easiest structure to start with. You manage transactions through platforms like Xero vs MYOB, operate the business yourself, and can apply for an Australian Business Number (ABN).
The Australian Business Register (ABR) states that a sole trader is the only owner and is legally responsible for all aspects of the business, including its debts.
This can work well for freelancers, consultants, tradespeople, and people testing a new idea. Administration is usually lighter, and business income and claims from our small business tax deductions checklist are included in your individual tax return.
The main drawback is personal liability. There is no separate legal entity between you and the business. If the business owes money or faces a claim, your personal assets may be exposed.
Tax can also become less attractive as profits rise because income is taxed at personal marginal rates.
Company: More Separation and Room to Scale
A company is a separate legal entity from its owners. Australian companies are registered with the Australian Securities and Investments Commission (ASIC) under the Corporations Act 2001.
Once registered, a company receives a nine-digit Australian Company Number (ACN). Most trading companies also have an ABN.
A company can make sense when the business is growing, hiring staff, entering larger contracts, retaining profits, or taking on more commercial risk.
Company liabilities generally sit with the company rather than automatically becoming the personal liabilities of shareholders. Directors can still become personally liable in some situations, so working with a tax accountant for ATO compliance helps ensure personal risk is managed.
Eligible base rate entities may pay a 25% company tax rate. Other companies are generally taxed at 30%.
A simple way to compare the initial tax impact is:
Potential initial tax difference = Taxable profit × (personal marginal rate − applicable company tax rate)
For example, assume $100,000 of profit would fall within a 37% personal marginal tax bracket and the company qualifies for the 25% rate.
$100,000 × (37% − 25%) = $12,000
This does not automatically mean a permanent $12,000 tax saving. If profits are later paid as dividends, further personal tax may apply after franking credits. The outcome depends on how profits are retained, reinvested, or distributed.
Company owners also need to understand Division 7A. Certain payments or loans from a private company to shareholders or their associates can be treated as dividends unless an exclusion or complying arrangement applies.
Trust: Flexibility With More Moving Parts
A trust works differently from a sole trader or company. A trustee holds and manages assets for beneficiaries.
A Discretionary Family Trust can suit family businesses, asset holding entities, and ventures involving SMSF property investment where flexible income distribution is important.
The trustee may decide which eligible beneficiaries receive trust income, subject to the trust deed and tax law. Beneficiaries are then taxed based on their own circumstances.
That flexibility can help with legitimate tax planning, but it also creates more administration.
Trust distribution resolutions are important. For discretionary beneficiaries to be presently entitled to trust income, trustees generally need to make an effective resolution by 30 June. Poor documentation, delayed financial statements for year-end tax lodgement, or a late resolution can affect who is taxed on the income.
Asset protection may also be stronger than operating personally, especially where a corporate trustee is used. However, protection depends on the trust deed, guarantees, transactions, and how the structure is managed.
Company vs. Trust vs. Sole Trader: Quick Comparison
| Factor | Sole Trader | Pty Ltd Company | Discretionary Family Trust |
|---|---|---|---|
| Setup | Simple | Moderate | More complex |
| Personal liability | High | Generally more separation | Depends on trustee and structure |
| Tax | Personal marginal rates | 25% for eligible base rate entities; otherwise generally 30% | Usually flows to beneficiaries based on distributions |
| Asset protection | Limited | Generally stronger | Can be strong when structured correctly |
| Profit distribution | Owner receives profit | Salary, dividends, or retained profit | Flexible distributions to eligible beneficiaries |
| Compliance | Lower | Higher | Higher |
| Best suited to | Small or lower-risk businesses | Growing businesses | Family groups and flexible planning |
Real-World Scenario: Moving From Sole Trader to Pty Ltd
Consider a Sydney consultant who starts as a sole trader.
In year one, revenue is modest. There are no employees and little contractual risk. The simple structure works well.
By year three, the business has staff, larger clients, stronger cash flow, consistent profits, and a plan to hire a virtual CFO for scaling. The owner does not need to withdraw every dollar for personal use.
At that stage, a Pty Ltd company may provide better separation, allow profits to remain in the business, and create a clearer structure for growth.
Changing structure is not simply changing the name on an invoice. The ABR notes that moving from a sole trader to a company or trust may require cancelling the existing ABN and applying for a new one.
Which Structure Is Right for Your Business?
Ask four questions. How much profit do you expect? How much commercial risk does the business carry? Do you need flexibility to distribute income? Do you plan to hire, borrow, bring in investors, or sell later?
A sole trader may suit a small operation. A company may work better for a business that is scaling. A trust may be useful where family ownership, asset planning, and distributions are important.
Sometimes the answer is a combination, such as a company acting as trustee of a family trust.
Before changing anything, speak with professionals who can model the tax, compliance, legal, and cash-flow consequences. Our guide to a small business tax accountant in Sydney CBD and tax business advisory services explains what to expect from professional support. You can also explore our business advisory services for help reviewing a structure against your actual numbers and growth plans.
If you are looking for a business advisor Sydney owners can turn to for practical guidance, focus on more than this year’s tax bill. The right structure should still work when the business is larger, more profitable, and carrying more risk.